As of January 1, 2027, companies applying IFRS standards will have to comply with IFRS 18, a new standard that significantly changes how they present their financial performance. Beyond accounting adjustments, this development poses a broader challenge for finance departments: having reliable data, consistent indicators and systems capable of producing more transparent financial information. This transition could also lead organizations to review their reporting practices and performance management tools.
IFRS 18: making financial performance clearer and more comparable
Published in April 2024 by the International Accounting Standards Board (IASB), IFRS 18, entitled Presentation and Disclosure in Financial Statements, will replace IAS 1. Its application will be mandatory for financial years beginning on or after January 1, 2027, with early adoption permitted.
This change addresses a difficulty encountered by investors and analysts: companies do not always present their performance using the same methods. Certain indicators, particularly operating profit, may therefore cover different realities from one organization to another, making comparisons more complex at times.
IFRS 18 seeks to reduce these differences by further harmonizing the presentation of results and strengthening the information disclosed in financial statements. It does not directly change companies’ economic performance or all recognition rules. Its main aim is to improve how results are structured, explained and communicated.
For finance departments, this development means looking beyond published financial statements alone. The calculation methods, classification rules and indicators used internally must also be reviewed to ensure greater consistency between the different types of information produced.
An income statement reorganized around new categories
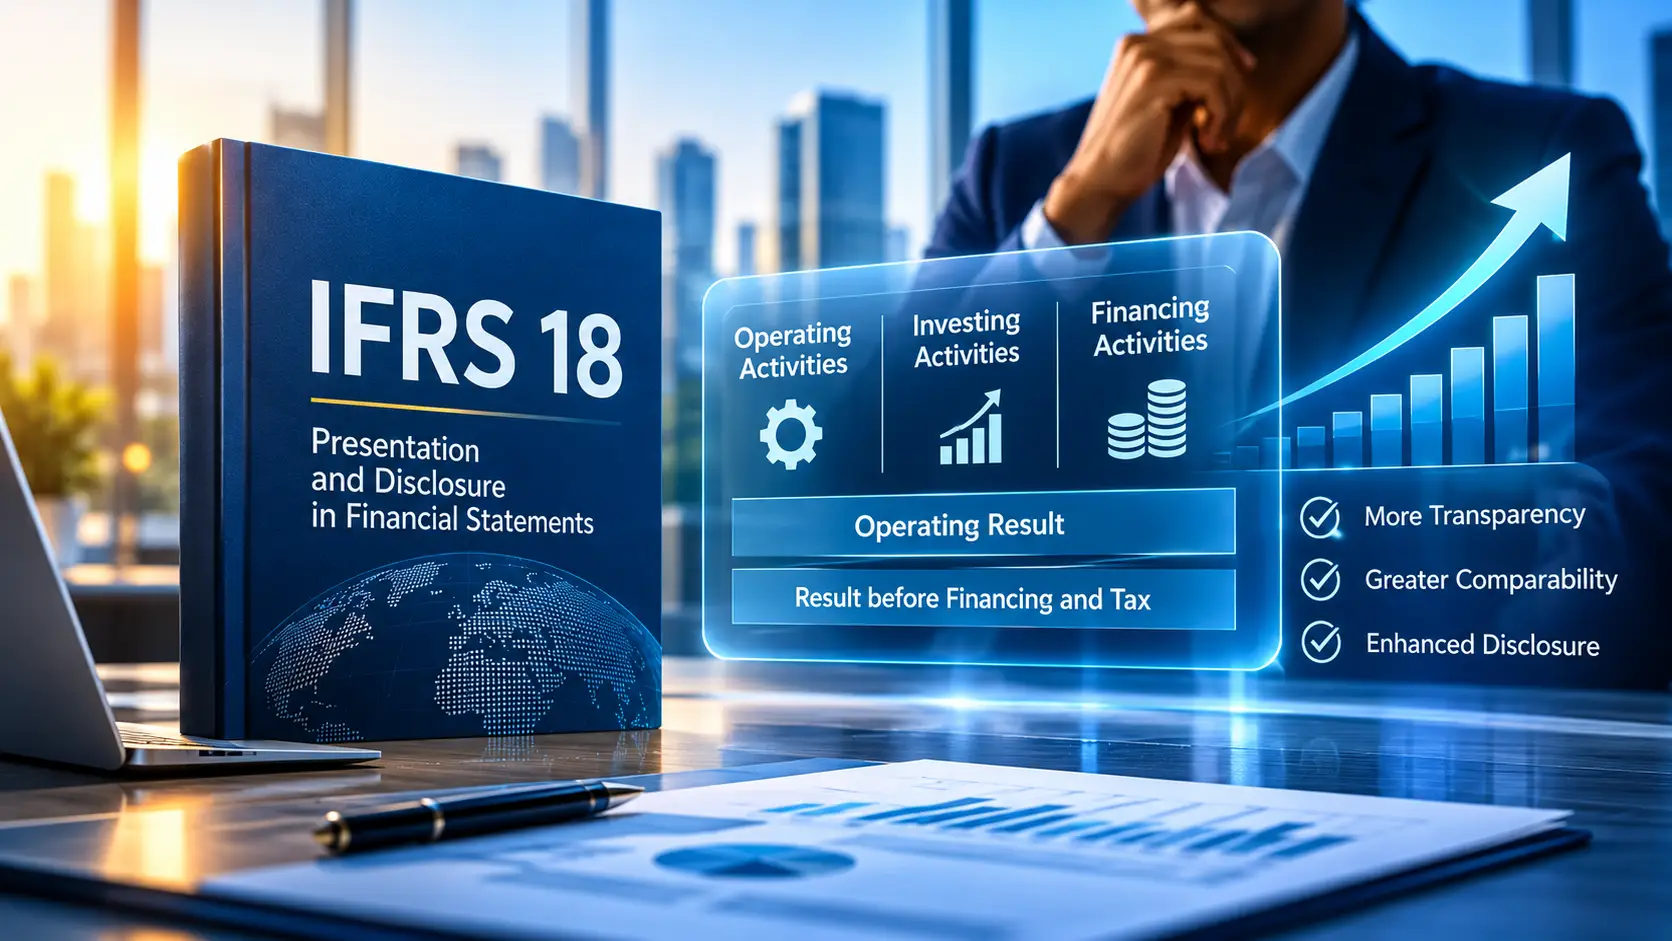
One of the most visible changes concerns the structure of the income statement. IFRS 18 introduces a classification of income and expenses into three main categories: operating activities, investing activities and financing activities. Items relating to income tax and discontinued operations are also assigned to separate categories.
The standard notably requires two subtotals: operating profit and profit before financing and income tax. The aim is to enable readers to better distinguish performance arising from the company’s operating activities from the effects of its investments and financing.
However, this new presentation requires analytical work. The classification of certain income and expenses depends on their nature and, in some situations, on the company’s main business activity.
For finance teams, the challenge will therefore be to verify that the classification rules applied in their systems correspond to the new requirements. Chart of accounts, consolidation models and existing reporting processes may require adjustments to produce the new subtotals reliably and consistently.
Management performance measures subject to greater transparency
Another important development is that IFRS 18 provides a more detailed framework for management-defined performance measures, known as Management-defined Performance Measures (MPM).
Companies regularly communicate additional indicators to explain their results: adjusted operating profit, profit before certain specific items, or adjusted measures used in their financial communications.
When these indicators meet the definition of MPMs under IFRS 18, the standard requires additional information in the notes to the financial statements. Companies must notably explain their definition, the reasons for using them and how they are calculated, as well as provide a reconciliation with the most directly comparable IFRS subtotal or total.
This requirement increases the need for documented calculation methods and rules shared across finance teams.
It also encourages finance departments to review their dashboards and management indicators. An indicator used to manage operations, presented to the executive committee or communicated to investors must be explainable and reconcilable with the underlying reference financial data whenever required by the standard.
Financial information requiring better-structured data
IFRS 18 also strengthens the principles governing the aggregation and disaggregation of financial information. Companies must distinguish between items with different characteristics and avoid overly broad groupings that could conceal material information.
The aim is to strike a balance between information detailed enough to be useful and a presentation structured enough to remain understandable.
This requirement highlights an often less visible issue: companies’ ability to ensure the traceability of their financial data. To explain a published amount, teams must be able to trace its origin, understand the calculation rules applied and identify any adjustments made.
When information comes from several systems or is subject to numerous manual manipulations, this traceability can become more difficult to guarantee.
Reporting quality therefore depends as much on data reliability as on its organization, circulation and the controls implemented throughout the financial production process.
Why reporting and consolidation tools are affected
Preparing for IFRS 18 is not limited to changing the presentation of the income statement. Depending on the complexity of their organization, companies may need to adapt their charts of accounts, classification rules, consolidation models and reporting processes.
Timing is also a key consideration. The first application of the standard requires comparative information to be presented for the prior financial year. Companies will therefore need to anticipate the production of comparable data for the comparative period and the first period presented under IFRS 18.
In this context, financial information systems play an important role. They must make it possible to manage the new presentation rules, secure processing, preserve data traceability and produce consistent financial statements.
EPM (Enterprise Performance Management) solutions can help meet these needs, particularly through their consolidation, financial reporting, performance measurement and data centralization capabilities.
They can also facilitate reconciliations between accounting data and management indicators, while reducing certain manual operations. Their suitability nevertheless depends on the existing architecture, the company’s needs and how processes are organized.
Adapting the tools must therefore be accompanied by consideration of how responsibilities are allocated among accounting, consolidation, management control and information systems teams.
IFRS 18 as a lever for evolving performance management
Although compliance with the standard is the first priority, IFRS 18 can also provide an opportunity to review certain management practices.
Better-defined indicators, documented calculation rules and greater consistency between financial and operational reporting can make it easier for executives to interpret results. They also help improve dialogue between finance teams and other functions within the company.
This development is particularly meaningful when organizations seek to bring their reporting, consolidation, budgeting and forecasting processes closer together. Better-structured financial information can then serve not only to meet disclosure obligations, but also to inform management decisions.
This does not mean systematically replacing existing tools. Some organizations may meet the new requirements by adapting their current environment, while others may need to consider more significant changes to their systems.
The priority is to assess actual needs, identify the limitations of the existing organization and determine the adaptations required.
Anticipating IFRS 18 to turn a constraint into an opportunity
IFRS 18 will take effect on January 1, 2027. For the companies concerned, the remaining time should be used to assess the standard’s impact, review the relevant processes and prepare any necessary adaptations to their financial systems.
Beyond compliance, this transition offers an opportunity to strengthen data quality, indicator consistency and reporting reliability. Above all, it highlights that producing relevant financial information depends not only on accounting rules, but also on the processes and tools used to apply them.
For finance departments, the challenge is therefore twofold: meet the new presentation requirements while building a more structured, transparent management environment better suited to decision-making needs.
How Pilotia can support companies through this change
Specializing in the advisory, selection and implementation of EPM solutions, Pilotia experts support organizations seeking to evolve their financial performance management systems.
In the context of IFRS 18, our support can focus on three complementary areas.
Assessing the existing performance management environment. An analysis of reporting processes, consolidation requirements, data flows and the capabilities of the tools in place makes it possible to identify any functional gaps and the adaptations to consider.
Identifying solutions suited to the company’s needs. When technological developments are required, the choice of a tool must take into account data complexity, existing systems, reporting requirements, available resources and budget. Pilotia’s independence from software vendors makes it possible to approach this selection without favoring a predetermined technology.
Structuring and implementing the EPM project. From formalizing functional requirements to selecting and implementing the solution, Pilotia supports companies in building a performance management environment consistent with their processes and objectives.
Contact us today to launch your project.